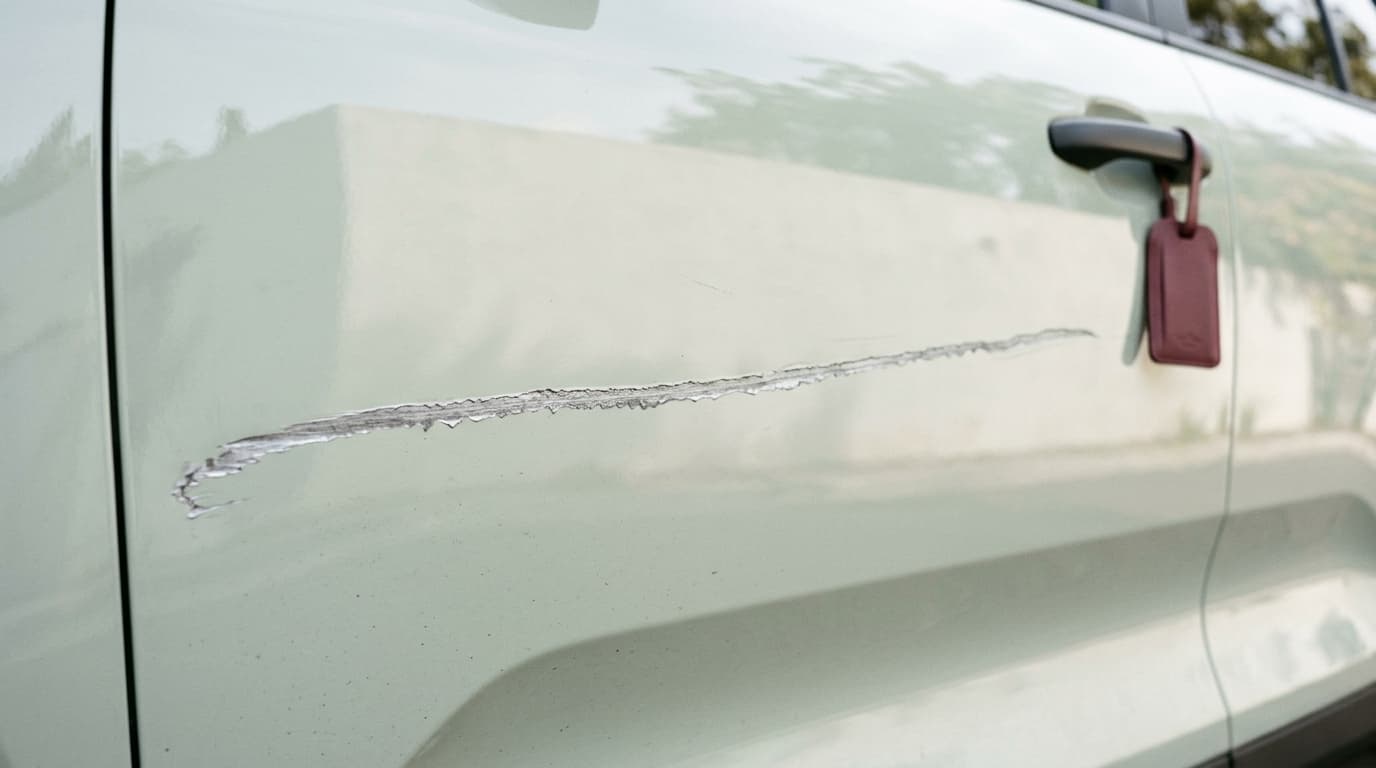
No, if all you hold is compulsory liability cover. In principle yes, if you hold full omnium, after the deductible. Under mini omnium the answer turns on a single line of your policy, and on that precise point the Belgian market does not speak with one voice.
Is vandalism to my car covered by insurance?
Only if you took out the guarantee that names it, usually material damage. Third-party liability insurance (RC), the only compulsory motor cover in Belgium, pays for the damage you cause to others. The screwdriver scratch running down your door is not part of it.
The table describes common practice on the Belgian market, not your policy. Your particular conditions, and only they, are what count.
| Cover held | Scratch, graffiti, bodywork | Smashed window | Slashed tyres | Deductible to expect |
|---|---|---|---|---|
| Liability only | No | No | No | Not applicable |
| Liability and glass cover | No | Rarely, if the act was deliberate | No | Glass deductible |
| Mini omnium | Often no, check | Depends on the wording | No in principle | Often zero, but no cover |
| Mini omnium, attempted theft | Damage from the break-in | Yes in principle, under theft | No | Theft guarantee rules |
| Full omnium | Yes in principle | Yes in principle | Yes with some insurers | Material damage deductible |
Two rows need explaining. The fourth first: a forced lock or a window smashed to steal from the car falls under the theft guarantee, which most mini omnium policies include, not under vandalism. Then the third, because it holds all the ambiguity of the subject.
Mini omnium and vandalism: the sources contradict each other
Wikifin, the financial education website run by the FSMA, the Belgian financial services and markets authority, describes mini omnium as cover limited « as a general rule » to fire, theft or vandalism, glass, natural forces and collision with an animal. Its omnium page, updated on 8 June 2026, therefore places vandalism in the smaller formula.
The product documents I reread in October 2026 say the opposite. Here are the four sources side by side.
| Source | Date | Vandalism under mini omnium? |
|---|---|---|
| Wikifin (FSMA), omnium page | June 2026 | Yes, « as a general rule » |
| Allianz, Car Plan information sheet | February 2023 | No: « only under a full Omnium » |
| Beobank (ACM Belgium), product information document | June 2023 | No: vandalism only appears in Full Omnium |
| P&V, omnium leaflet | February 2016 | No: material damage, « vandalism or following an accident », outside mini omnium |
Nobody is wrong. Wikifin describes a cautiously worded market average, and insurers describe their own product. Readers, though, often conclude they are covered because an official source says so, when their policy files vandalism under a formula they never signed.
That is exactly why I never recommend a formula without having read its exclusions.
Scratch, slashed tyre, wing mirror: which guarantee applies?
The cause matters more than the damage itself. The same broken wing mirror can fall under four different guarantees, each with its own deductible and conditions, and the cause you declare is what moves the file from one to another.
- Scratch or graffiti on the bodywork: material damage, so full omnium in most Belgian policies.
- Side window smashed by a vandal: usually material damage too. Our reading of glass cover shows that the same window can be paid if a stone cracked it and refused if someone broke it on purpose.
- Window or lock forced to steal: theft guarantee, with its own locking and prompt-reporting requirements.
- Punctured or slashed tyres: often excluded on their own. Allianz's Car Plan sheet carves out the opposite exception and covers tyres when the damage comes « from an act of vandalism ».
- Headlight or wing mirror torn off: material damage, unless a glass extension names them expressly.
- Belongings stolen from the car: rarely covered by motor insurance. The same Allianz sheet excludes personal effects carried in the vehicle.
A word on tyres. The most generous clause on the market remains an exception, and most policies I read treat a puncture as wear and tear unless other damage comes with it.
What deductible applies to a vandalised car?
The material damage deductible, as a rule, and it weighs heavily on small claims. Several Belgian policies set a fixed deductible linked to the car's catalogue value, others an English-style excess or a proportional one.
A worked example with hypothetical amounts. Your car is scratched along two doors and a wing, and the body shop quotes 1,400 euros. With a fixed 800 euro deductible, the insurer pays you 600 euros. With a 250 euro deductible, it pays 1,150 euros. Same scratch, same quote, and a 550 euro gap that was decided on the day you signed.
Some formulas tie the deductible to how you react. According to CallMePower's AG Insurance page, updated in June 2026, the Flexi deductible on the Top Omnium is waived if the vandalism is reported to the police within 24 hours. A clause like that changes the real value of a policy far more than any welcome discount.
Light scratch, 300 euro quote? Compare before you claim.
Does vandalism raise your bonus-malus?
No. The Belgian 0-22 scale only reacts to liability claims where you are at fault, as explained in our article on bonus-malus. Allianz sums it up in one sentence on its sheet: there is only a bonus-malus in liability cover.
Your premium may still move at renewal if several omnium claims follow one another. That is pricing, not malus.
And if the vandal is identified?
You can claim the repair from him, but his insurer will not pay. Article 62 of the Insurance Act of 4 April 2014 bars an insurer from covering anyone who caused the loss intentionally. His family liability policy (« RC familiale ») therefore stays silent, and your claim targets his personal assets, with all the uncertainty that implies.
The Common Guarantee Fund (Fonds commun de garantie) is no way out either: it compensates victims of road accidents caused by an uninsured or unidentified vehicle, not victims of a vandal on foot. Legal protection cover pays the costs of that claim, provided its civil recovery guarantee covers this kind of dispute.
Checking your policy in six minutes
Open your particular conditions as a PDF and switch on search. Our guide to particular conditions shows where each mention sits.
- Type « vandalisme ». Note the chapter it appears in: material damage, mini omnium, or nowhere.
- Check that this chapter is among the guarantees you actually hold, not just in the product's general conditions.
- Search for « pneu » (tyre) and read the whole sentence: flat exclusion, or an exception for vandalism.
- Note the material damage deductible, and any waiver tied to a prompt police report.
- Note the reporting deadlines. The product information document for Beobank's car insurance, for example, allows eight working days to report a claim and 24 hours to file a police report after a theft.
- Read the grounds for forfeiture of cover: a late police report and an incomplete claim form are the two most frequent reasons for refusal on this kind of file.
Six searches, none of which requires reading the whole policy.
Not covered: which guarantee should you add?
On a recent car parked in the street or in a public car park, moving to full omnium is the only complete answer to vandalism. Our mini omnium vs full omnium comparison draws the boundary guarantee by guarantee, and the article on wear and tear recalls that beyond a certain age the payout becomes too small to justify the premium.
On an older car the question changes. A material damage deductible of several hundred euros already absorbs most scratches, and the premium money is sometimes better kept as savings. I will not decide for you: the level of risk depends on where the car sleeps, and you know that better than any pricing engine.
To line those up across policies, the comparison tool sets guarantees side by side, the ranking of the best car insurers details what each company covers and refuses, and the quiz helps you settle the right level of cover for your car in two minutes. The product information document for Beobank's car insurance is public and shows where vandalism sits in a Belgian range. Where a disagreement over the scope of a guarantee persists, the Insurance Ombudsman, the free Belgian complaints service for insurance customers, examines consumer complaints, and the FSMA supervises the conduct rules of insurers and intermediaries.
This site informs and compares. It is not an insurance intermediary and gives no individual recommendation: your particular conditions, and only they, decide.
Formules & garanties comparator
Compare all formules & garanties side by side.
Compare now
Frequently asked questions
Grégory conseille des automobilistes belges sur leurs contrats d'assurance depuis plus de dix ans. Il décortique les formules RC, mini-omnium et omnium, compare les compagnies du marché belge et traduit les conditions générales en langage clair. Sa règle : aucune recommandation sans avoir lu les exclusions.