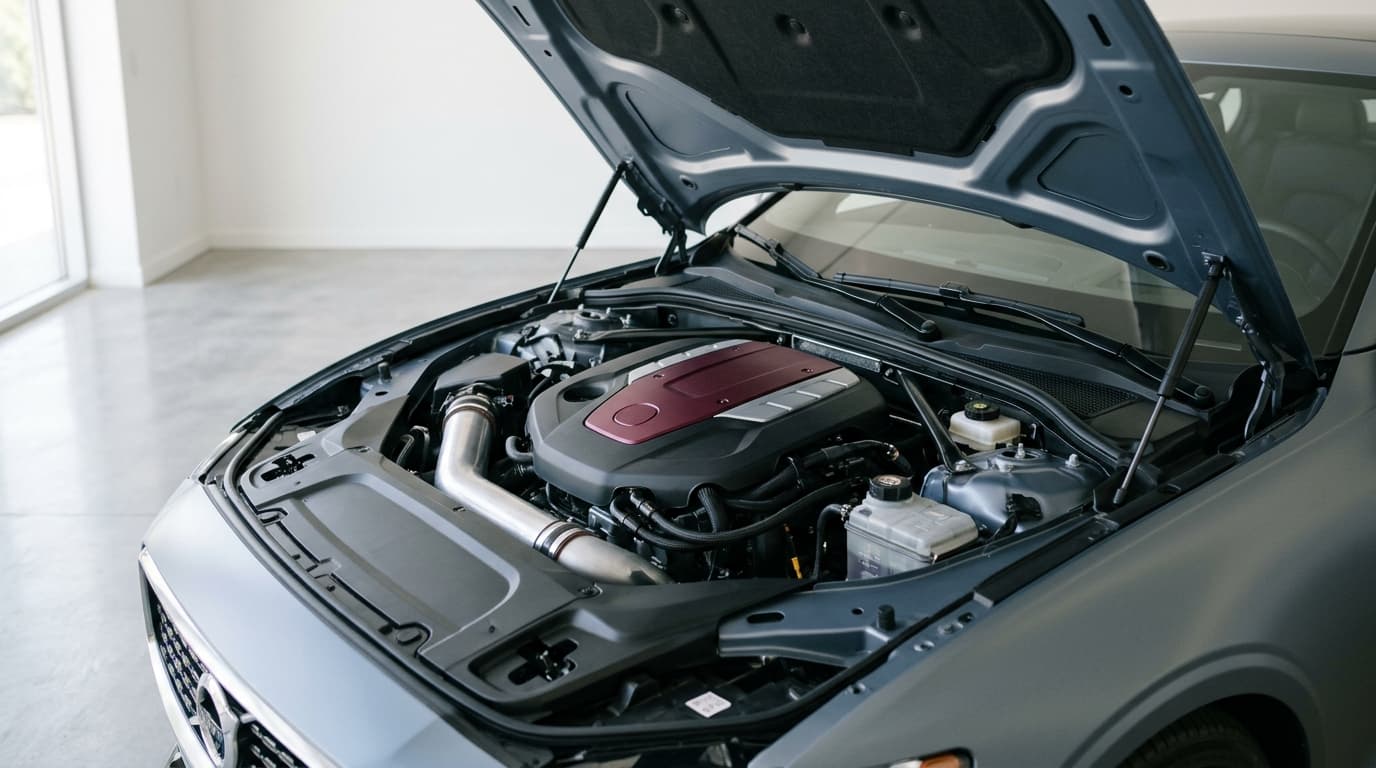
No. In Belgium, omnium, even full omnium, does not pay for a mechanical breakdown: it rules out wear, poor maintenance and manufacturing defects. Three other arrangements can take it on, and only one of them is an insurance contract. Mixing them up costs money, sometimes the price of an engine.
Three arrangements, only one is insurance
A car that breaks down involves four possible players, and each follows a different logic. The motor insurer pays for an event coming from outside. The seller answers for a defect present at delivery. The manufacturer honours its own commercial warranty. Only a specialist insurer, often through a broker or a lender, sells an extended warranty against sudden breakdown.
The table below describes common practice on the Belgian market. It does not replace your particular conditions, which are the only ones that count.
| Arrangement | Who pays | For how long | Trigger | Typical exclusions |
|---|---|---|---|---|
| Legal guarantee | The professional seller | Two years from delivery | A lack of conformity, presumed present at delivery | Abnormal use, normal wear |
| Manufacturer or garage warranty | The manufacturer or garage | The term written in the contract | A defect on the covered list | Skipped maintenance |
| Extended warranty | An insurer, via broker or lender | One year renewable, or the length of the credit | Sudden failure of a listed component | Wear parts, missing maintenance, waiting period |
| Omnium and mini omnium | The motor insurer | The term of the policy | An outside event: accident, theft, fire, natural forces | Wear, manufacturing defect, poor maintenance |
The last line explains everything else.
What does Belgian omnium say about mechanical breakdown?
It takes it out of the guarantee. The information document for the motor insurance distributed through the Toyota network in Belgium, which consumers can read online, lists among the omnium exclusions mechanical damage caused by wear, poor maintenance and manufacturing defect. The same document adds tyres, outside covered damage, and damage linked to overloading. Another insurer will word it differently; the logic stays the same.
The reason lies in the nature of the risk. Insurance pays for a chance event. The wear of a belt or a turbo is not chance, it is time passing, and no contract can price it in advance without billing it in advance.
What does get through is mechanical damage following a covered event: an engine drowned after a flood falls in principle under natural forces, and gnawed cables fall, with some insurers, under the omnium rodent guarantee. The breakdown itself stays at your expense.
Full omnium: the word that misleads
People often read « omnium complète » as « everything is covered ». The word « complète » describes the presence of material damage, meaning the accident you cause yourself. It does not describe cover for wear.
Mini omnium, for its part, covers in principle fire, theft, natural forces, collision with an animal and glass breakage, without the accident. The mini omnium vs full omnium comparison shows that boundary guarantee by guarantee, and the article on mini omnium details its content. Neither includes a « breakdown » line.
One detail weighs more than it seems. Even when mechanical damage is paid, wear and tear can reduce the payout on an older car, and the deductible applies on top.
Does the seller's legal guarantee come before insurance?
Yes, and it comes before buying any insurance. When you buy from a professional seller, Belgian law gives you a two-year legal guarantee. Since 1 June 2022 the seller is presumed liable for any defect appearing during those two years, whereas the presumption used to last only six months, as the FPS Economy points out.
Test-Achats, the Belgian consumer organisation, confirmed on 9 October 2026 that the two-year guarantee remains in force. The new Book 7 of the Civil Code, applicable to contracts concluded from 1 September 2027, will replace the hidden-defect guarantee with a guarantee against lack of conformity, which can be invoked for ten years provided the buyer proves the defect existed at least in embryo at delivery. Until then, purchases stay under the current rules.
One classic trap remains. The legal guarantee does not target normal wear, and it protects only a purchase from a professional. Between private individuals it does not apply. For a used vehicle, the length and conditions are in the sales contract and on the FPS Economy website, to read before paying for an extension that would duplicate it.
What is a Belgian extended warranty worth?
It is worth what its list of components and its exclusions promise, no more. I read two public ones, which do not follow the same logic.
The VdH (Vander Haeghen) extension, taken once the manufacturer's warranty has ended, covers engine, gearbox, electrics and electronics, transmission, steering, brakes, air conditioning and suspension. It is taken for one year with no commitment beyond that, with a renewal proposal each year if the vehicle remains eligible. Acceptance is reserved to the company, for a car under ten years old and under 100,000 km. Reimbursement per claim is capped at 30,000 euros including VAT, depending on the formula chosen.
The « extension de garantie » insurance sold with a credit at Alpha Credit, issued by Cardif, backs its assistance with Touring. Its waiting period lasts as long as the manufacturer's or seller's warranty, the contract stops when the vehicle turns ten, and it applies in Europe and the green card countries.
The exclusions overlap from one product to the next:
- wear parts: pads and discs, shock absorbers, exhaust, spark plugs, batteries, bulbs, tyres, bodywork;
- skipped maintenance, or maintenance done with non-original parts, when they caused the failure;
- the waiting period, during which a breakdown is not covered;
- certain components, listed in the general conditions, which change with the vehicle's age when you join;
- professional vehicles and those that need no driving licence.
A worked example, with invented amounts. An eight-year-old saloon with 85,000 km, outside manufacturer warranty, suffers a gearbox failure: the quote comes to 4,200 euros. Under omnium, the garage turns the file down, and so does the insurer. Under an extension taken before the breakdown, the file is admissible, subject to maintenance and the cap. Had the car shown 105,000 km when you signed up, no extension of that type would have accepted it.
When the engine fails under omnium: the cases that pass
The test remains the event. An engine damaged by a flood, a fire or a crash falls under the matching guarantees, with their deductible. An engine seized for lack of oil falls under maintenance, so under nothing.
Checking your policy in six lines
Open your PDF and switch on search. Our guide to reading particular conditions shows where each mention sits, and forfeiture of cover explains what can cancel a right you already hold.
- Type « usure » (wear). Note which exclusion the word appears in and what it covers.
- Type « vice de construction » or « défaut de fabrication » (manufacturing defect), and read the whole sentence.
- Search « entretien » (maintenance). Many contracts tie cover to regular servicing.
- Look for « consécutif » (consequential) or « dommage indirect ». A breakdown that causes a crash changes guarantee.
- Note the deductible and the cap of each guarantee that would touch the engine.
- Find the waiting period of any extension, which pushes back the first covered breakdown.
Should you buy an extended warranty?
Sometimes not, and it is the answer nobody has an interest in giving you. If you bought the car from a professional less than two years ago, the legal guarantee already covers you. If the vehicle is worth less than a big repair, the extension protects an asset no longer worth the premium. And if you drive little, the premium money sometimes protects you better as savings.
It makes sense in one specific case: a recent car, expensive to repair, out of manufacturer warranty, that you keep for a long time. The cost of an automatic gearbox or on-board electronics then justifies comparing.
To set formulas side by side on those lines, the comparison tool lines up the guarantees and the ranking of the best car insurers sets out what each company covers and refuses. The quiz settles the level of cover your car needs in two minutes. For a recent purchase, the article on insuring a used car lists the points to check, and the one on breakdown cover deals with breaking down on the road, which is a different guarantee.
Belgian car insurance contracts are governed by the Insurance Act of 4 April 2014. The rules on consumer goods guarantees are published by the FPS Economy, and Test-Achats detailed the Book 7 reform in October 2026. Where a disagreement over the scope of a guarantee persists, the Insurance Ombudsman, the free Belgian complaints service for insurance customers, examines consumer complaints, and the FSMA, the Belgian financial services and markets authority, supervises the conduct rules of insurers and intermediaries. The documents cited are public: the VdH extended warranty and the Alpha Credit information document detail their exclusions.
This site informs and compares. It is not an insurance intermediary and gives no individual recommendation: your general and particular conditions, and only they, count.
Formules & garanties comparator
Compare all formules & garanties side by side.
Compare now
Frequently asked questions
Grégory conseille des automobilistes belges sur leurs contrats d'assurance depuis plus de dix ans. Il décortique les formules RC, mini-omnium et omnium, compare les compagnies du marché belge et traduit les conditions générales en langage clair. Sa règle : aucune recommandation sans avoir lu les exclusions.